
Basis compression and new CME derivatives in Bitcoin markets
Institutional capital exited basis trades as the three-month Bitcoin futures basis fell below the two-year Treasury yield. Market signals show a defensive shift toward downside protection as Deribit 25-delta Put/Call skew reached +4.2%p despite high Bitcoin prices.

Institutional capital exits basis trades
Institutional players closed basis trades as the three-month Bitcoin futures basis fell below the two-year Treasury yield for 157 consecutive days starting in February 2026. This unwinding pushed CME Bitcoin futures open interest to its lowest point since February 2024. Traders who bought spot Bitcoin through ETFs and shorted CME futures to capture the spread found the trade unprofitable because yields no longer exceeded risk-free rates. This failed basis trade forced significant institutional capital out of the market. As the basis narrows, the divergence between spot and futures prices disappears and removes the incentive for arbitrageurs to hold positions. The contraction in open interest reached $7.2 billion in early April as liquidity rotated toward offshore perpetual swaps. Leveraged funds held 4,243 long against 11,483 short standard Bitcoin contracts as of August 4. This was a net short of 7,240 contracts or roughly 36,200 BTC. Because the basis trade relies on a positive carry in contango, the narrowing spread eliminates the profit motive for those using ETFs as the long leg. As Bitcoin surged above $81,000 after a spring slump that saw prices drop close to $60,000, the annualized basis had previously peaked at 15.3% in January 2025 before falling. Will these retreating arbitrageurs return when Treasury rates drop?
Derivatives signals show defensive shifts
The 8-hour funding rate hit -0.0082% across exchanges, which marked the first negative conversion in eight weeks. Simultaneously, the Deribit 25-delta Put/Call skew reached +4.2%p, a move that signaled higher demand for downside protection. Market participants pay more for puts than calls to hedge against price drops. Even with Bitcoin prices near $86,300, the 1-month implied volatility of 36.30% stays below the 20-day realized volatility of 42.30%. The 25-delta skew at +4.2%p reflects a market that prioritizes downside protection because traders are paying higher premiums for puts than for calls to manage risks against sudden price declines in the coming weeks. You should observe how these signals interact with the 30-day implied volatility. Bitcoin perpetual futures open interest reached $62 billion, a 41% increase over the 2025 annual average, which reveals a structural expansion in leveraged positions. This expansion occurs alongside a $6.44 billion notional value options expiry on Deribit and an OI-to-Volume ratio of 14.8x. The current market structure favors defensive hedging over aggressive basis capture. The 1-week skew reached +6.8%p, which confirmed that hedging demand remains concentrated in the most immediate contracts.
CME expands crypto product granularity
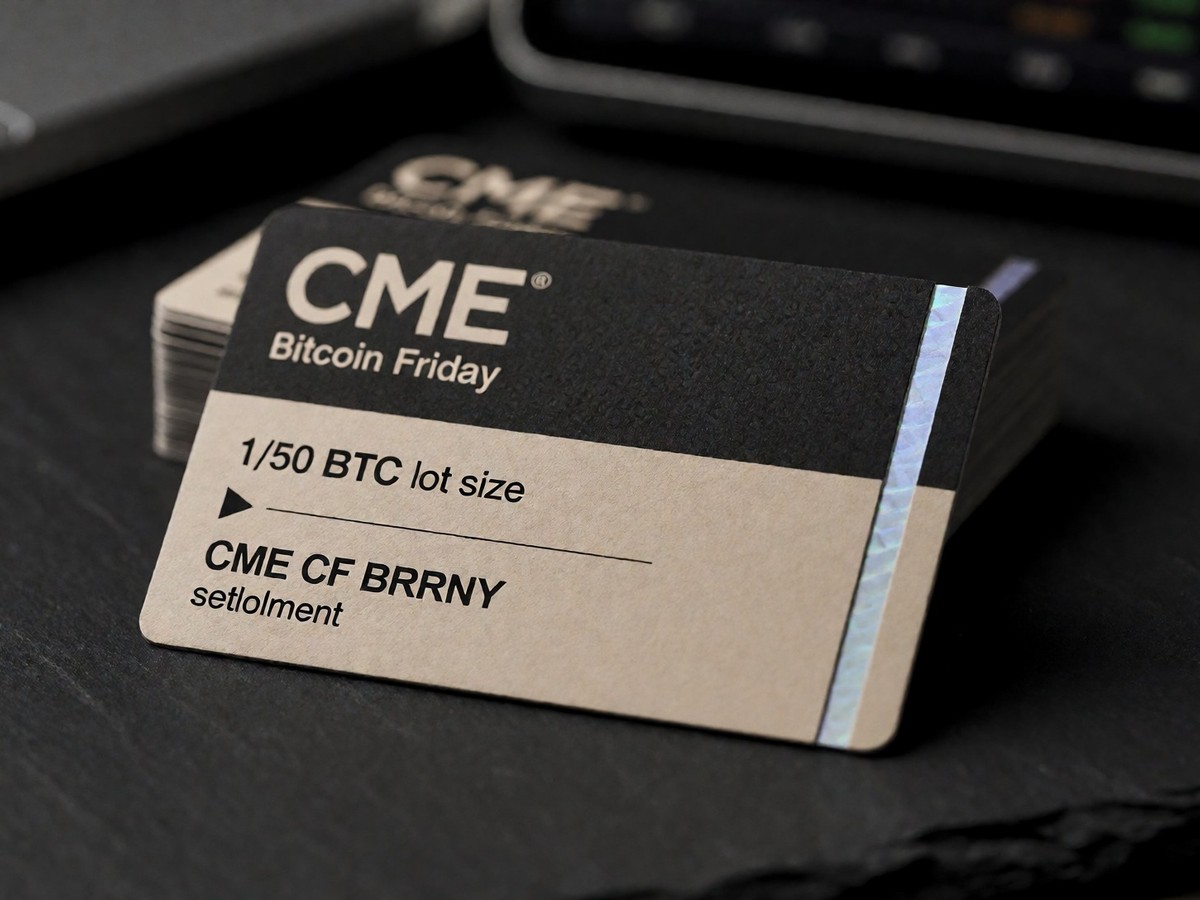
CME Group expanded its crypto suite by launching Bitcoin Friday futures and daily options. These products help investors manage weekend volatility and fine-tune exposure. The Bitcoin Friday futures contracts, which launched in late September, consist of 1/50 BTC lots and settle to the CME CF Bitcoin Reference Rate New York Variant. Traders use these smaller contracts to mitigate weekend price moves.
| Product | Size | Settlement |
|---|---|---|
| Bitcoin Friday Futures | 1/50 BTC | CME CF BRRNY |
| Bitcoin Volatility Futures | N/A | CME CF BVX |
| Standard Bitcoin Futures | 5 BTC | USD |
| Micro Bitcoin Futures | 0.1 BTC | USD |
The exchange also introduced daily-settled options on these Friday futures in February. These options expire each business day from Monday through Friday. Market makers use these tools to manage exposure as they react to price fluctuations. The launch follows the June introduction of Bitcoin Volatility futures. These settle against the 30-day forward-looking BVX index. This index derives its data from real-time order book information from the CME Bitcoin options market. CME also implemented nearly 24/7 trading on its Globex platform in early 2026. This shift allows institutional traders to adjust positions during weekends. Average daily volume for CME crypto derivatives reached 407,200 contracts in 2026. This was a 46% year-over-year increase.

Join the discussion