
HKMA Expands Stablecoin Sandbox
The HKMA expanded its regulatory sandbox for stablecoin issuers to clarify market rules following the US GENIUS Act. This move supports a global market projected to reach $750 billion, allowing institutions to test digital cash mechanics while maintaining banking stability.

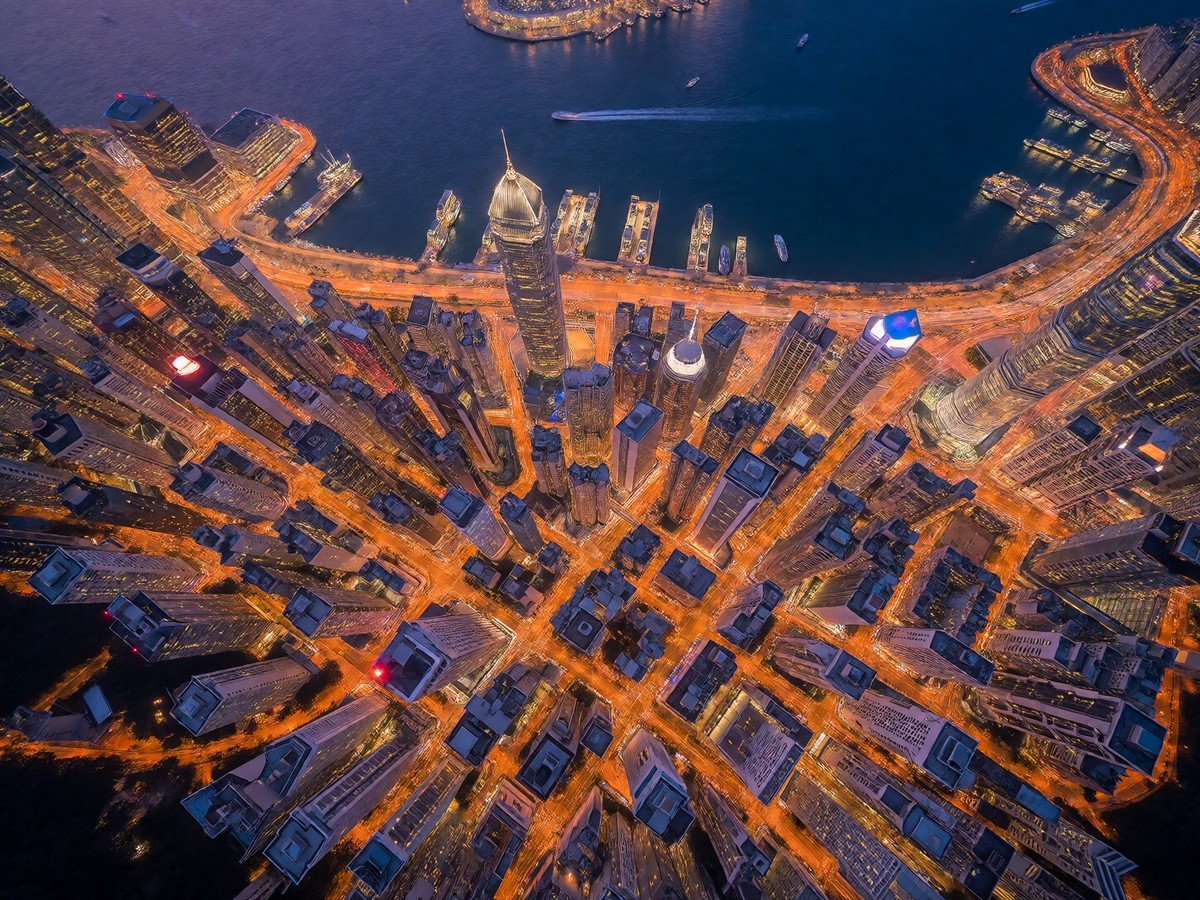
The Hong Kong Monetary Authority (HKMA) has expanded its regulatory sandbox for stablecoin issuers, a move that directly addresses the lack of clarity in the local market. This expansion follows the passage of the GENIUS Act in July 2025, which established the first federal framework for stablecoins in the United States. By mirroring this legislative progress, the HKMA signals that digital cash is now a legitimate asset class rather than an experimental technology. The central bank aims to maintain Hong Kong’s status as an international financial centre while ensuring the stability and integrity of the banking system.
Regulatory Framework and Market Context
Stablecoins function as digital dollars, backed by reserves of fiat currency on a one-for-one basis. For every $10 billion in circulation, the issuer must hold at least $10 billion in high-quality liquid assets such as Treasury bills. Tether and Circle dominate this space, accounting for approximately 90% of the global market, which currently stands at roughly $300 billion. Analysts project this figure could reach between $500 billion and $750 billion in the coming years, potentially hitting the trillion-dollar mark if growth trajectories align. The primary driver remains the crypto market, where stablecoins facilitate trades in native cryptocurrencies. A secondary factor involves non-US persons in emerging markets who view dollar stablecoins as a superior store of value compared to volatile local currencies.
You likely know that stablecoins are not deposits, but the distinction matters for risk management. Unlike bank deposits, stablecoins do not guarantee redemption at par, and several instances of de-pegging have occurred where the price fell below the $1 net asset value. Furthermore, under the GENIUS Act, stablecoins cannot pay out interest, setting them apart from money market funds. This creates a unique intersection where investors accept volatility risks for the benefit of instant, 24/7 settlement capabilities. The HKMA’s sandbox expansion allows institutions to test these mechanics within a controlled environment before full licensing.
| Feature | Stablecoins | Bank Deposits |
|---|---|---|
| Redemption Guarantee | No (de-peg risk) | Yes |
| Interest Payment | No | Yes |
| Settlement Speed | Seconds to minutes | Days |
| Regulatory Backing | GENIUS Act / HKMA Sandbox | Banking Ordinance |
Operational Implications for Issuers
The expansion provides a clear pathway for authorized institutions to engage in securities business related to digital assets. The HKMA maintains a register of relevant individuals to ensure staff are fit and proper, a statutory condition for any registered institution. This transparency helps the public ascertain who they are dealing with, reducing counterparty risk in a rapidly evolving sector. However, the transition is not without friction; KYC and AML requirements remain complex, and liquidity management poses significant challenges for new entrants.
Cross-border payments to emerging markets represent the most compelling use case, as current rails are costly and slow. Yet, skepticism persists regarding consumer adoption for everyday purchases, with many users preferring established platforms like Venmo or PayPal. The institutional side offers a more robust argument for digital cash, particularly when factoring in compliance and fraud prevention. Whether the sandbox will successfully bridge the gap between experimental tech and mainstream infrastructure remains an open question. The HKMA continues to monitor the Exchange Fund and banking stability, ensuring that any innovation does not compromise the Linked Exchange Rate System.
Join the discussion