
The Wyoming SPDI charter and federal regulatory friction
Wyoming's SPDI framework, which saw Kraken receive a pilot master account in 2026, faces ongoing tension with federal regulators. Legal battles persist as the Federal Reserve denies access to firms like Custodia Bank while the OCC asserts preemption over state laws.

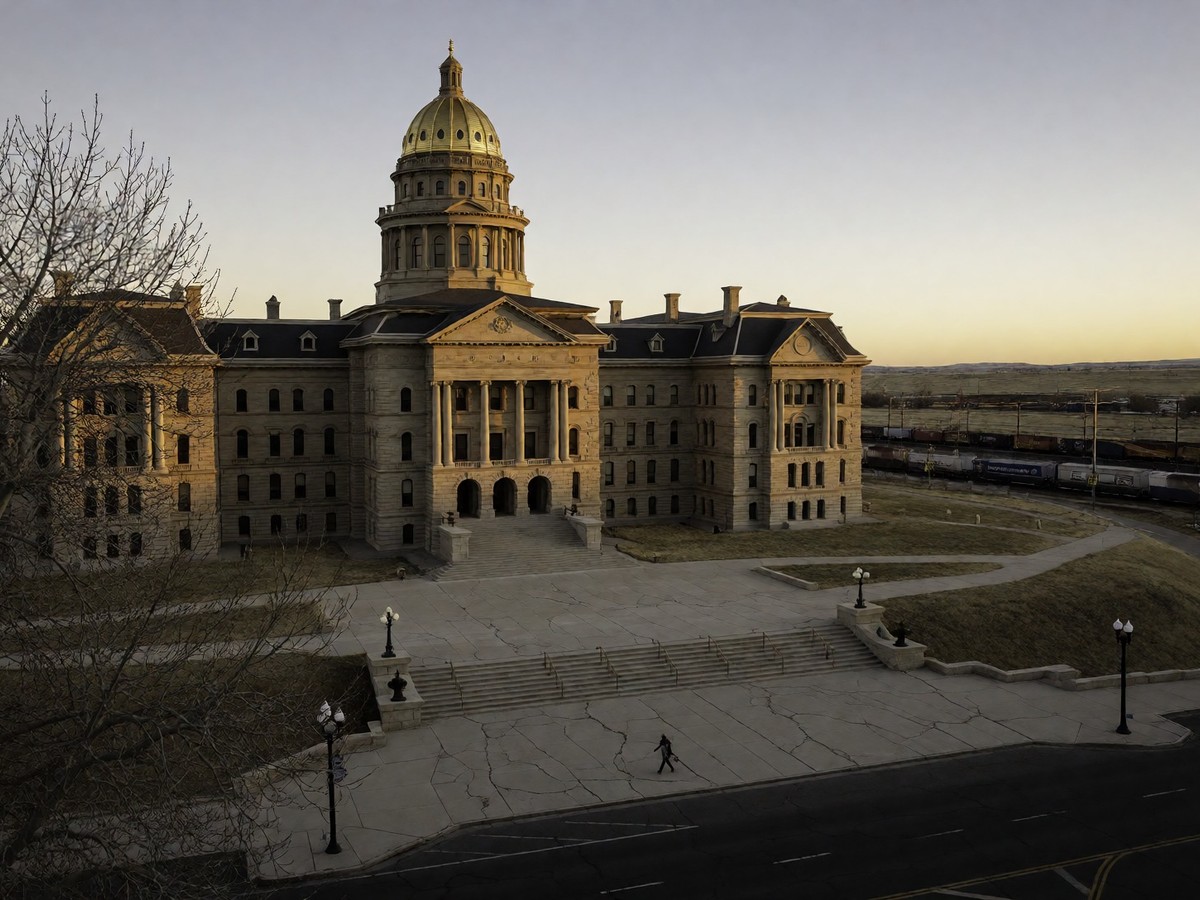
Wyoming enacted House Bill 74 in 2019 to establish the Special Purpose Depository Institution (SPDI) charter. This framework creates non-lending banks that hold fiat reserves equal to 100% of customer deposits to prevent bank runs. These institutions focus on custody, payment services, and asset servicing rather than traditional lending. Following the 2019 legislation, the Wyoming State Banking Board approved Kraken’s SPDI charter application in September 2020. Kraken formed Kraken Financial in Cheyenne to handle digital assets. Avanti Bank & Trust, later renamed Custodia Bank, won the second SPDI charter in October 2020. Wyoming Deposit & Transfer became the third recipient in June 2021, and Commercium Financial received the fourth charter in August 2021.
| Institution | Charter Type | Primary Focus |
|---|---|---|
| Kraken Financial | Wyoming SPDI | Digital asset custody and payments |
| Custodia Bank | Wyoming SPDI | Institutional crypto custody |
| Wyoming Deposit & Transfer | Wyoming SPDI | Tokenized asset custody |
| Commercium Financial | Wyoming SPDI | Asset tokenization |
| Telcoin Digital Asset Bank | Nebraska DADI | Stablecoin issuance and custody |
Federal Reserve Access and Legal Battles
The Federal Reserve denies certain access to crypto-focused banks despite state laws permitting applications for master accounts. The Federal Reserve Board denied Custodia Bank’s application in 2023 because it cited safety and soundness risks regarding the company’s crypto-heavy business model. In October 2025, the 10th Circuit Court of Appeals affirmed the Federal Reserve’s discretion to deny master accounts to Custodia Bank. The court rejected Custodia’s challenge to the lower court ruling that the central bank holds discretion over who receives access. This legal battle follows Custodia’s 2022 lawsuit against the Federal Reserve Board and the Federal Reserve Bank of Kansas City regarding application delays.
The Federal Reserve granted Kraken’s SPDI a one-year pilot master account on March 4, 2026. This permission allows Kraken to settle directly on Fedwire without using intermediary banks. The approval includes limitations and restrictions tailored to Kraken’s specific risk profile and business model. While Kraken operates as a Tier 3 applicant, the Federal Reserve introduced a tiered system for reviewing applications in 2022. In contrast, Nebraska’s lone DADI, Telcoin Digital Asset Bank, obtained its charter in November 2025 but has not secured a Fed master account. Do these pilot programs establish a permanent pathway for all state-chartered digital asset institutions?
Preemption Conflicts and State Law Challenges
Federal regulators use preemption to limit state authority over national banks. On May 15, 2026, the Office of the Comptroller of the Currency (OCC) adopted the Escrow Powers Rule and the Preemption Rule. These rules allow national banks to decide whether to pay interest on funds in real estate escrow accounts. On August 11, 2026, Oregon and nine other states, including New York and California, filed a lawsuit in the U.S. District Court for the District of Oregon to challenge these rules. The plaintiffs argue the OCC manufactured a conflict to preempt state consumer protections.
The states claim the OCC violates the Dodd-Frank Act, which requires the agency to act on a case-by-case basis and prohibits field preemption. The lawsuit asserts the OCC lacks substantial evidence to prove that state interest-on-escrow laws prevent or significantly interfere with national bank powers. The plaintiffs note that the Ninth Circuit ruled in Kivett v. Flagstar Bank in 2025 that state laws do not necessarily conflict with federal bank powers. This legal tension mirrors the divide between state-level innovation and federal regulatory control. The OCC maintains that its determination follows the Barnett standard to ensure banking flexibility.
Join the discussion