
Regulatory clarity replaces crypto enforcement spikes
SEC enforcement actions dropped to 372 in 2025 as Chair Paul Atkins redirected resources toward fraud. A joint SEC-CFTC interpretation now classifies 16 assets, including XRP and Ethereum, as digital commodities to provide market stability.

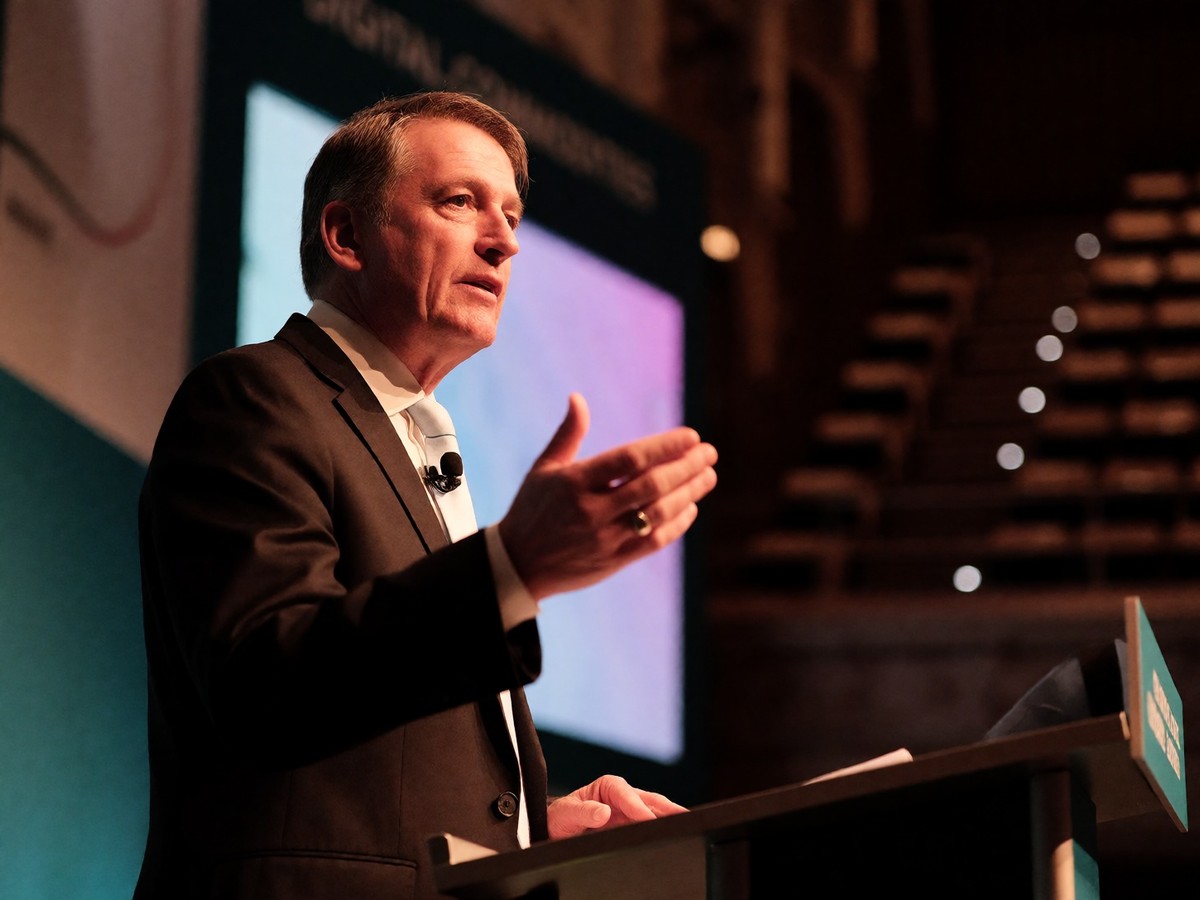
SEC enforcement numbers crater
The SEC’s pivot to rule-making works because enforcement numbers have plummeted. The SEC concluded 372 enforcement actions in 2025, a 29% drop from the 524 cases in 2024 and a massive decline from the peak of 663 enforcement actions recorded in 2023. Paul Atkins, who took office as SEC Chair on 21 April 2025, redirected resources away from technical rule violations toward fraud and market manipulation. He closed 1,095 enforcement cases in 2025 without taking further action. You should notice the shift from the 30 crypto enforcement actions of 2022 to the current posture of Project Crypto. While enforcement dropped, the agency received 53,753 tips and complaints in 2025, an increase of 19% over the previous year. This influx of complaints persists despite the agency’s stated shift in focus. This follows the March 16 resignation of Margaret Ryan and the appointment of David Woodcock as enforcement director on May 4. In 2022, the agency brought 30 enforcement actions against digital-asset participants, a 50% increase from the 20 actions in 2021. During that 2022 period, the SEC charged 79 defendants or respondents, of which 56 were individuals and 23 were firms. Of those 2022 actions, 14 involved initial coin offerings, and 57% of those included a fraud allegation.
A new taxonomy for digital assets
The March 17, 2026, joint SEC-CFTC interpretation provides the stability builders need. This move avoids the uncertainty of the CLARITY Act. The framework defines five categories: digital commodities, digital collectibles, digital tools, stablecoins, and digital securities. Commissioner Hester Peirce proposed safe harbours for startups and investment contracts that currently sit in OMB review. The following 16 assets now hold official digital commodity status:
| Asset Name |
|---|
| XRP |
| Ethereum |
| Solana |
| Cardano |
| Chainlink |
| Avalanche |
| Polkadot |
| Stellar |
| Hedera |
| Litecoin |
| Dogecoin |
| Shiba Inu |
| Tezos |
| Bitcoin Cash |
| Aptos |
| Algorand |
This list includes both established networks and community-driven meme tokens. The interpretation clarifies that protocol mining, protocol staking, wrapping, and airdrops of non-security crypto assets are not themselves securities activities. Digital collectibles include tokens acquired for artistic or cultural purposes, while digital tools function as access rights or governance mechanisms. This regulatory clarity complements the GENIUS Act, which was enacted on 18 July 2025 to regulate payment stablecoins following the House bill passage. Under that Act, permitted issuers must be a subsidiary of an insured depository institution, a federal-qualified nonbank issuer approved by the OCC, or a state-qualified issuer with issuance capped at $10 billion. These stablecoins require 1:1 reserves limited to cash and short-dated Treasuries, but the Act prohibits interest payments to holders.
CFTC expands its reach
The CFTC is aggressively asserting its territory through new rules and litigation. On 5 October 2026, the commission issued an advance notice of proposed rulemaking regarding retail crypto asset transactions. This notice asks for industry feedback on whether to create a specific registration for crypto asset markets. This comes as the CFTC continues its legal fight over prediction markets, having filed litigation in April 2026 against Illinois and Connecticut to assert federal authority over platforms like Kalshi. The commission also filed a complaint against Michele Spagnuolo for alleged insider trading on Polymarket and charged Goliath Ventures with an alleged $400 million fraud scheme.
The commission also ordered UBS Financial Services to pay $8 million over supervision failures affecting its Anti-Money Laundering systems on 31 July 2026. On 7 July, the CFTC charged a North Carolina commodity pool operator and his company with fraud. Does the federal push for preemption over state gambling commissions eventually reach the Supreme Court?
Join the discussion